
AI summary
Summary of article:
The Fed is expected to remain on hold on Wednesday, but Washer’s potentially hawkish press conference tone may not be necessary due to falling US bond yields and the approaching election.
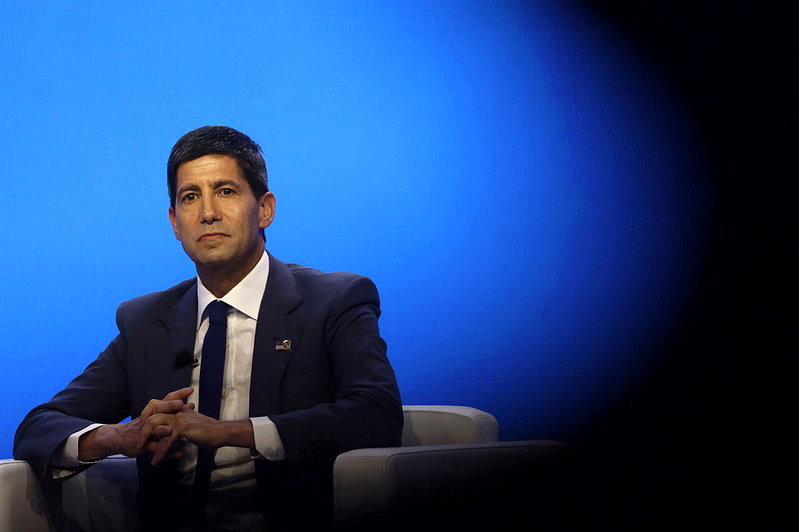
This is what the market generally expectsfederal Reserve (The Fed) is expected to keep interest rates unchanged at Wednesday’s policy meeting, and some analysts expect the Fed chairmanwashoo Given the recent increase in inflation, this statement may be even more “disgusting”. However, well-known economists believe that this time there is no need for the washer to sing a “disgusting” note.
Brooks, a senior fellow at the Brookings Institution and former chief economist at the Institute of International Finance (IIF), believes that long-term US public debtproduce This rapid increase was key to Washer’s “dox” stance at the central bank’s annual meeting in Jackson Hole. But now, the French debt crisis has prompted funds to seek refuge in the US Treasury market, which has pushed US long-term bond yields lower. From this perspective, there is no need for Washer to sing the “Eagle” tune again at the press conference after the Fed’s decision-making meeting on Wednesday.
He said the Fed did not raise interest rates at its July 29 meeting, which led to a surge in the market. The US bond yield curve shows a “bearish intensification” (long-term bond yields rise more than short-term bonds). Criticism that the Fed has lost its credibility in fighting inflation has attracted the attention of senior US officials. As a result, Treasury Secretary Besant unexpectedly announced the repurchase of long-term bonds on August 19, and Washer also expressed a “disgusting” stance in his Jackson Hole speech, leading to Fed policymakers unanimously deciding to raise interest rates on September 16.
What will happen this time? The market generally expects the Fed to decide on holding after Wednesday’s meeting as the midterm elections approach. Attention turned to how “disgusting” Washu’s press conference speech was.
First, the 10-year US Treasury bond yield rose once this month to 5.3%. Now that it has fallen from its peak, it has naturally limited the need to sing the “eagle” tone at the Fed’s press conferences. After all, if the washer’s “eagle” tone is surprisingly high this time, it will definitely give rise to questions: If it is so “eagle”, why were the interest rates not raised this time?
Secondly, Washu cited three reasons for switching to “Eagle” at the press conference after the meeting in September: economic growth was stronger than expected, inflation did not decline rapidly, and oil prices rose again (at that time, Saudi Arabia’s East-West oil pipeline was attacked).
Now, concerns about an artificial intelligence (AI) bubble have weakened US growth prospects, inflation remains persistent, and oil prices have risen even higher. Overall, concerns about weak growth should temper the Fed’s “doxious” tone. A series of previous statements from Fed policymakers have softened the “hateful” tone.
Brooks speculated that since this decision-making meeting is so close to the US midterm elections on November 3, the Fed should keep as low a profile as possible. If it is too “disgusting”, it will cause unnecessary attention and political controversy. In other words, now is not the time to scare the market with “hateful” messages, even in press conferences.
Summary FAQ
-
Since inflation is still under upward pressure recently, and there are concerns that the Fed’s anti-inflation stance is not strong enough, some analysts speculate that his speech after the policy meeting may be biased toward a more hawkish signal.
-
He believes that long-term government bond yields have fallen from their highest levels, and the French debt crisis has also caused money to flow into the safety of US bonds. Now that the market pressure has subsided, there is no need for Washer to deliberately issue a strong message.
-
Since the meeting is close to the midterm elections, if Washer’s remarks are too harsh, it may easily cause market panic and unnecessary political controversy. Therefore, the Fed is more likely to choose to keep a low profile to avoid giving rise to outside interpretations.