
AI summary
Summary of article:
Although the amenities of Florida’s 55+ retirement communities are attractive, the recurring expenses such as HOA, CDD, insurance and medical care are huge, so many retirees are still afraid to sign a contract after viewing homes.
thousands of people every yearretire people come to communicateFlorida Although he was impressed by The Villages, a community built through competition with “Retirement Paradise”, he did not sign a contract; And the main issue that emerged in almost every conversation had nothing to do with the community’s amenities.
Financial website 24/7 Wall St reported that there are several communities in Florida designed specifically for people over the age of 55 that aim to compete with The Villages. In these communities amenities include golf carts and pickleball lessons, and the monthly fee is posted and buyers factor it into their appraisal when considering the price of a home. These fees include homeowner association (HOA) fees, community development district (CDD) amortization fees, and club dues, which continue even after the mortgage is paid off.
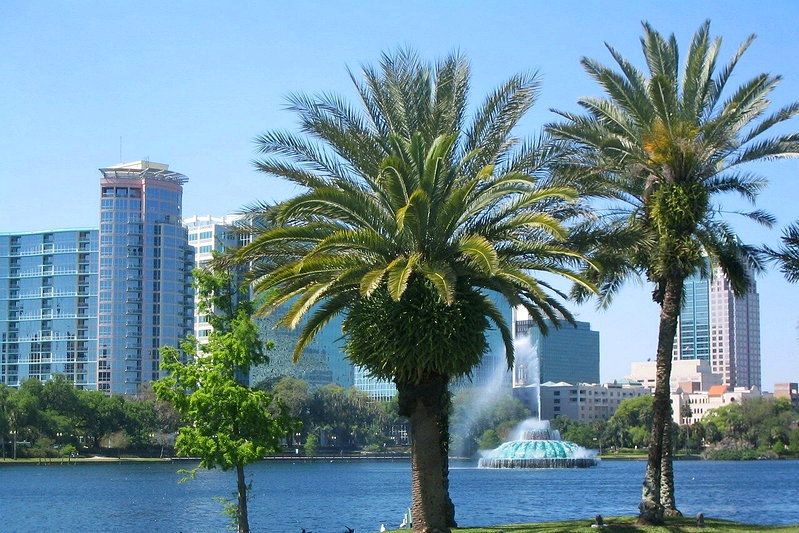
Taking the area around Orlando as an example, HOA fees, CDD amortization fees and club dues in the 55+ community are about 376 to 653 yuan per month; The CDD part alone will increase by 128 to 220 yuan per month, and even after the bond is repaid, operation and maintenance costs will continue indefinitely. In addition to the basic HOA fee, some communities also charge an additional mandatory amenity fee of 195 yuan, bringing the actual monthly expense to the mid-range of more than 400 yuan.
The Villages has a different fee structure, with new buyers paying a monthly convenience fee of $204, plus an annual CDD amortization fee of $1,200 to $3,000 and an annual maintenance amortization fee of $600 to $1,400. The Villages adds together the various service charges that homeowners pay individually, so when they are compared to each other, they need to be converted into an amount for the entire year.
Let’s say a couple pays cash for a resale home in Solivita, a retirement community with a median price of $375,000. Florida’s income-adjusted state and local tax burden is $5,110, the lowest in the United States; The exception is insurance premiums, which average $3,000 to $4,000 per year.
Other annual expenses are $6,000 in HOA, CDD and club dues, $4,500 in property taxes after applying for the owner-occupied home exemption, $3,500 in homeowner’s insurance and wind damage insurance, $11,870 in Medicare Parts B and D and supplemental health insurance for two people, and $3,000 in dental, vision exams and out-of-pocket medical expenses. $13,000 in groceries and club restaurant purchases, $4,500 in utility and phone bills, $5,500 in golf cart and vehicle replacement costs, $8,000 in travel, club dues and gifts, $5,000 in maintenance fees and emergency reserves, and $2,500 in federal withdrawal taxes, totaling $67,370.
After the cost of living adjustment (COLA) in 2027, the average older couple will receive $3,355 in Social Security benefits per month, or $40,260 per year. If the above $27,110 shortfall in the annual budget is met with a 4% withdrawal rate, $677,750 will need to be prepared; If calculated with a 3.5% withdrawal rate, approximately $775,000 would be required. If two people delay receiving social security benefits until the age of 70, the amount can be increased to about 49,900 yuan, the difference will also be reduced, and the 3.5% target amount will also be reduced to about 499,000 yuan.
Village community utility fees are linked to the Consumer Price Index (CPI) and cannot increase more than the CPI. Uniform HOA fees have no such upper limit and depend on the budget of the board of directors, which includes items such as club insurance and employee salaries. Over time, this fee will become a recurring expense that will increase with inflation.
Summary FAQ
-
The point is not whether the facilities are great or not, but whether the monthly and annual fixed expenses are too high. HOA, CDD, club dues, insurance and medical bills pile up on top of each other, causing retirees to worry about long-term cash flow shortages.
-
Generally, communities often charge separate HOA, CDD and club fees, and monthly fees tend to be lower; The village separates the facility fee, CDD amortization and maintenance amortization, but it is still considerable when converted into an annual fee.
-
Taking a couple who bought a home for $375,000 as an example, their annual expenses were $67,370. After deducting Social Security benefits, there is still a gap of $27,110, indicating that they need to build up a large amount of assets to sustain their lives after retirement.