
AI summary
Summary of article:
The Wall Street Journal reported that homeowners who took advantage of low interest rates and chose an ARM mortgage will now face a significant increase in monthly mortgage payments due to the interest rate reset. Some people are looking for ways to deal with the problem like refinancing or relocating.
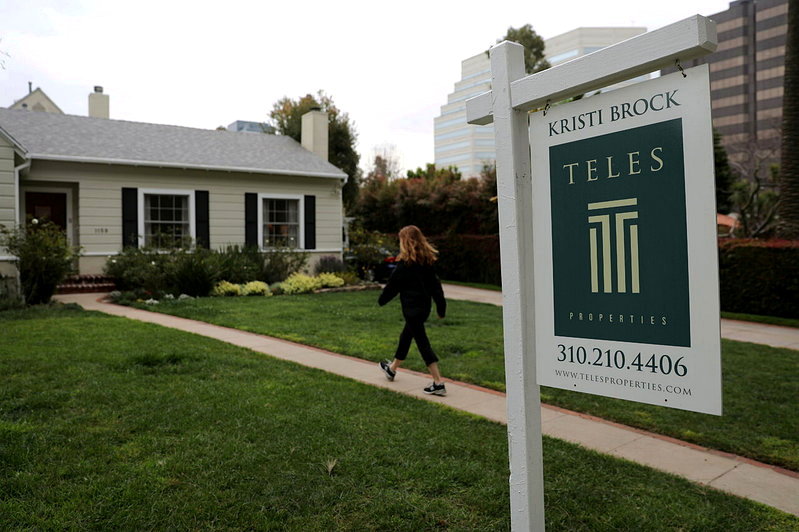
The Wall Street Journal reported on the 28th, which was previously reportedinterest rate Hundreds of thousands of consumers who took out adjustable-rate mortgages when they were at historic lows will face a steep increase in their monthly mortgage costs as interest rates readjust. Homeowners applying for 7-year ARM mortgages in 2020 are the largest group whose mortgage interest rates are about to reset. The average monthly mortgage repayment is estimated to increase by 43%, which means an increase in expenses of 1,269 yuan.
The report notes that when Andrew Hecker, who bought a home in Minneapolis, applied for an ARM mortgage in 2019, he didn’t think there would be much risk. At that time, the initial interest rate of ARM mortgages provided by financial institutions was about 1.25 percentage points cheaper than the 4% of a traditional 30-year fixed rate mortgage. Heck plans to look forward seven years before interest rates adjust.
Heke’s mortgage interest rate may rise from 2.75% to 7.75% in January next year, and the minimum monthly mortgage repayment amount will rise from 6,800 yuan to 9,300 yuan. “Basically, this means that any extra money I pay is used to pay interest,” he said.
“Looking back in 2026, I think the decision taken at that time was a bit foolish. I should have chosen a fixed-rate loan,” he said.
The appeal of an adjustable rate mortgage is that you can enjoy a favorable interest rate for three to 10 years, and then have the interest rate adjust again when market interest rates fluctuate.
The risk with ARM mortgages is that if market interest rates rise when they reset, the monthly mortgage payments will be higher than for a traditional fixed-rate mortgage. If market interest rates go down, or if the borrower moves before the end of the preferential period, they can avoid higher costs.
Mortgage Bankers Association data shows that in the week ending October 16, 2020, 10.5% of mortgage applications were for ARMs, up from 6.3% earlier this year.
According to data from Intercontinental Exchange, 186,000 ARM mortgagees will face interest reset next year. The average monthly payment may initially increase to 645 yuan, and the increase may reach 745 yuan after exceeding the upper limit. The largest group of them are homeowners who applied for 7-year ARM mortgages in 2020. The average monthly mortgage repayment is estimated to increase by 43%, equivalent to an increase in spending of 1,269 yuan.
Brad Case, chief residential economist at the real estate website Homes.com, said that if you don’t plan to stay in the home forever, ARM mortgages can actually save money, but the risk is that “you may not be ready to move when interest rates reset.”
Herco currently has $600,000 remaining on the mortgage to repay, and he is considering various options, including refinancing with a 7-year ARM with an initial interest rate of 5.75%. He said he was unsure whether he would continue to live here at that time.
Summary FAQ
-
This is because this type of loan initially offers lower interest rates and will later be adjusted again according to the market. If the current interest rate is high, monthly payments will increase significantly after the reset, and may even be more expensive than a fixed-rate mortgage.
-
Homeowners are the largest group applying for 7-year ARM mortgages in 2020. It is estimated that the average monthly mortgage repayment will increase by 43%, to about 1,269 yuan, making them the most affected group in this wave of reset.
-
Minneapolis homeowner Heck’s monthly payment was originally about 6,800 yuan, which may increase to 9,300 yuan in the future; There are 186,000 ARMs in the overall market that will be reset, which suggests that rising interest rates will rapidly increase home affordability.