
AI summary
Summary of article:
New mortgages that are reviewed based on potential rents rather than individual properties are attracting investors looking to renovate and rent out abandoned communities, but they also come with risks of fraud and foreclosure.
The Wall Street Journal recently reported that some long-abandoned neighborhoods have been replaced by newloan Reincarnation occurs, and the loan evaluation is based on the ability of the house to be rented out in the future.Rent Instead of being based on income, assets and income of the borrower, some people start investing through this type of loans for landlordsreal estate . The new loans will help inject money into cities across the country that are in desperate need of revitalization, including Indianapolis, Baltimore, Detroit and Memphis.
Real estate investment opportunities are rare in East Cleveland, Ohio. The federal government labeled much of the city “definitely declining” in the 1930s, and warned banks about the risks of providing home loans.
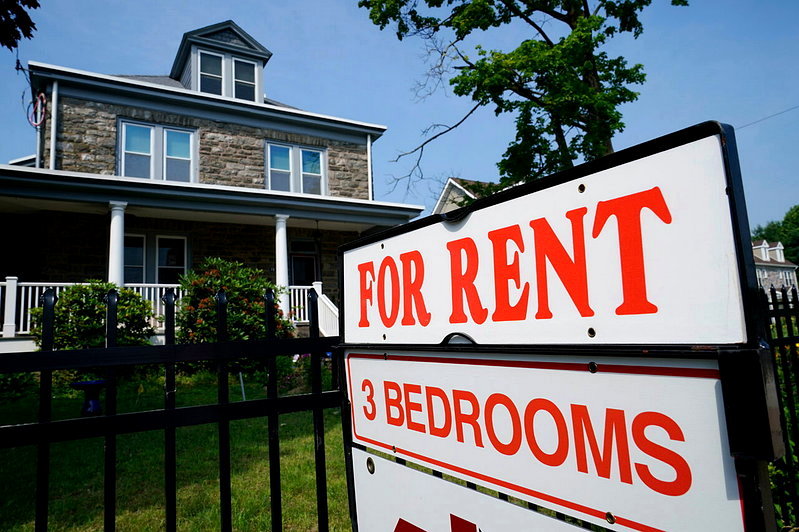
The local community has been in desolation and decline for decades. A new type of mortgage loan targeted at landlords has emerged, helping investors buy vacant and dilapidated homes, renovate them, and rent them out.
“There are people flipping houses on every street,” said Ashley Wilson, a Florida investor who is currently engaged in house flipping in East Cleveland.
The traditional home loan review process requires assessing the repayment capacity of the borrower, looking at the credit score, debt-to-income ratio and condition of the property. Financial institutions are generally less willing to provide loans in communities with lower income levels and lower property values.
New loans are based on home value and potential rental income rather than the borrower’s income. Lenders often do not need to see proof of a borrower’s income.
Loan-service coverage ratio loans, launched in the mid-2010s, are a fast-growing private loan industry that attracts borrowers with flexible underwriting, simple processes, and speed.
Investor Tabitha Giddens said that when she applied for this new type of loan, she unexpectedly discovered that the process was much easier when she renovated a home in West Philadelphia, Pennsylvania and rented it out. He said the paperwork alone was quite organized.
The report noted that many small investors used the new loans to obtain short-term financing to purchase and renovate homes and then sold the homes within a year and a half. If the home cannot be sold at the desired price, apply for refinancing and rent the home out. This new type of loan has become a “safety net” for many real estate investors trying to pick up cases they otherwise wouldn’t touch.
Wilson said he had no objection to investing in the city’s worst neighborhoods, “because that’s where you can get the most bang for your buck.”
She said she originally wanted to invest in real estate in her hometown of Florida, but housing prices in Florida have become too high. In comparison, he also bought a house in the vicinity of Cleveland for 24,000 yuan.
The report notes that there are risks in new mortgage loans as well. Loose underwriting processes and the introduction of various services by lenders have led to an increase in fraud cases, and a wave of foreclosures. Communities that have just recovered could be dragged down again.
Summary FAQ
-
It mainly looks at the home’s potential future rental income and property value rather than the borrower’s salary, credit score or property condition, so it is more attractive in areas where traditional banks are unwilling to do so.
-
Because such loans make it easier for investors to buy vacant, dilapidated homes and renovate them for rentals, money flows into areas that have long been deprived of investment, fueling renewal in neighborhoods like East Cleveland.
-
Due to loose underwriting and multiple service mechanisms, cases of fraud are on the rise and foreclosures may also increase. If the market weakens, communities that have just begun to recover could be hit again.