
AI summary
Summary of article:
Huang Renxun’s related investigation and regulatory concerns have caused Huida’s share price to decline, but AI demand, product competitiveness and development prospects have not changed. Whether to buy on dips or not depends on the risk tolerance of investors.
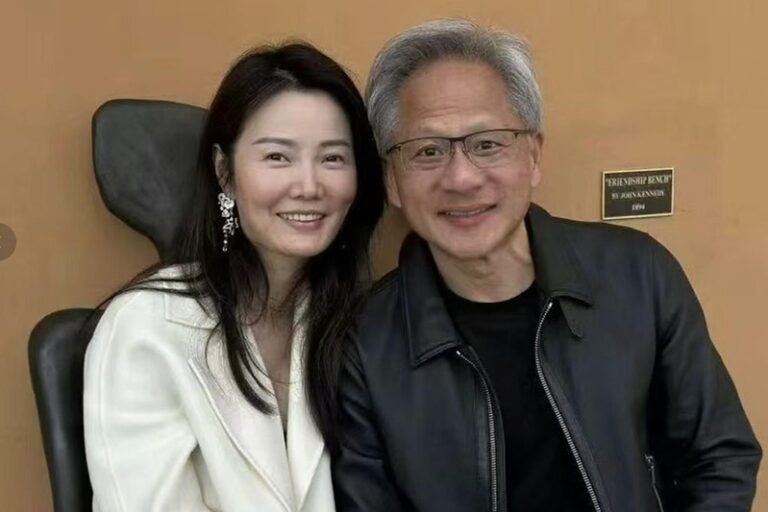
Huida (Nvidia)’s share price has been bullish this year and this week tooJen-Hsun Huang Doubts about Chinadetective Due to the investigation, relationships between people have come under pressure. The stock price is currently trading at 19 times estimated earnings, but demand for artificial intelligence (AI) and chip quality remains unchanged. Whether to buy on dips or not depends on the risk tolerance of investors.
The Motley Fool reported that Huida’s stock price has been one of the main winners of the AI revolution. That’s because Huida has built an AI empire, providing the world’s fastest AI chips, namely graphics processing units (GPUs), and a full portfolio of supporting products and services. As AI customers rush to buy Huida chips, Huida launches new versions of chips, and demand often exceeds supply. This results in dramatic increases in profits, with revenues and profits increasing by double and triple digits.
Investors saw this trend at the start of the AI boom, sending the stock price up 1,100% from the beginning of 2023 to the end of last year. The trend of Huida and other AI giants this year has been relatively up and down, mainly because investors have become cautious about the AI industry. Investors are concerned about rising inflation in the United States and are questioning whether data center spending will be maintained at current levels.
Just this week, particularly bad news came out of Huida. Huida has launched an investigation into Chief Executive Jen-Hsun Huang’s ties to a man whom US intelligence agencies say is a Chinese spy. In this environment, is Huida a good opportunity to buy on dips, or is it a stock to avoid?
Huida’s share price fell 4.2% the next trading day, leaving the stock price at about 19 times estimated earnings per share. Given the company’s growth record and future prospects in the AI boom, the stock is very cheaply priced at this price.
The main risk facing the company now is that Huang may step down or be forced out. Since he is a visionary leader who has led the company for decades, and Huida has not yet announced a succession plan, investors may not like this situation, which may also put pressure on stock price performance.
Another risk is that US lawmakers could tighten regulations or further restrict chip exports to China, which could hinder the company’s future growth.
The decision to buy or avoid Huida now depends on your own risk tolerance. If you are a cautious investor, you may choose to wait for the investigation results to be released before entering the market. Although Jen-Hsun Huang intends to continue leading the company and the board of directors has expressed confidence in him, there will be continued uncertainty until the investigation is completed, which could be detrimental to the stock price in the short term. Any potential resignation of Jen-Hsun Huang would also be bad news.
Having said that, the current turmoil has not shaken the demand in the AI market, nor affected the quality of Huida’s chips and innovations. Active investors with well-diversified portfolios may consider buying some shares of Huida at its current extremely low valuation and wait out the storm.
Summary FAQ
-
The main reason was that Huida launched an investigation to clarify the relationship between Huang Renxun and the person whom the US intelligence agency called a Chinese spy. The news created skepticism among investors and the share price fell 4.2% in a single day.
-
Because Huida currently trades at around 19 times estimated earnings per share, this P/E ratio is considered relatively cheap compared to its record of rapid growth amid an AI boom, strong chip demand and profit expansion.
-
The article believes it depends on risk tolerance. Conservative investors may wait for investigation results and regulatory changes to become clear before entering the market; Active investors with good diversification may consider deploying in batches when valuations are low.