
AI summary
Summary of article:
In response to the murder of a Taiwanese woman in Japan, which has been questioned by the outside world as being linked to high-value insurance fraud, the Financial Supervisory Commission said that the existing system has prevented insurance fraud through mechanisms such as written consent, underwriting inquiry and claim notification.
There is a Taiwanese woman named JingJapan A man was stabbed to death in a hotel, and the outside world suspected that she and her husband had obtained money fraudulently.Insurance Related to gold. The Financial Supervisory Commission today pointed out that there are multiple check points to prevent insurance fraud, including that third-party death insurance contracts must obtain the written consent of the insured, and there are also review or reporting mechanisms at the three stages of solicitation, underwriting and claims settlement.
On the 19th, a Taiwanese woman surnamed Jing was stabbed to death in a hotel in Japan. Japanese police arrested the suspect, a Taiwanese woman surnamed Yang. Jing’s husband, a man named Li, was suspected of marriage fraud and taking out high-priced insurance for Jing. He was detained when he entered Taiwan from Japan and released after review by the Tainan District Prosecutors Office.
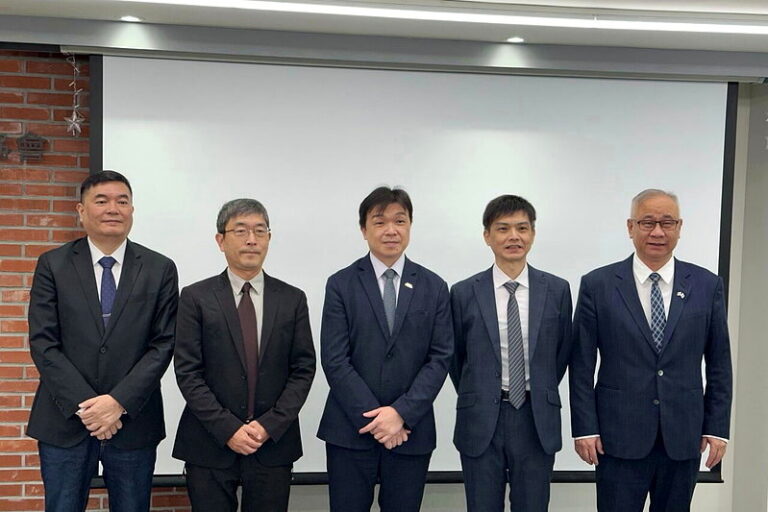
On how to prevent fraudulent insurance incidents, Cai Huoyan, deputy director of the Insurance Bureau of the Financial Supervisory Commission, said at a regular press conference today that there are several preventive mechanisms in place. Article 16 of the Insurance Law states that the applicant has an insurable interest in the life or body of his or her family members, those on whom he or she relies for living or education expenses, debtors, and those who manage their own property or interests.
Cai Huoyan pointed out that if a death insurance contract is purchased by a third party, according to Article 105 of the Insurance Law, the contract must obtain the written consent of the insured and the insurance amount must be agreed upon before the contract is valid, so as to avoid the situation of wrongly purchasing insurance without the insured’s consent.
In addition, Cai Huoyan also said that in the first stage of solicitation, the lawyer actually needs to record the purpose and motivation of the insured in the solicitation report or business report in the form of underwriting evaluation.
In the second stage of underwriting, Cai Huoyan explained that according to the insurance industry recruitment and underwriting claim settlement methods, and the insurance industry recruitment and underwriting operation control self-regulation regulations, when an insurance company receives an insurance case, it should go to the insurance notification system to check the insured’s insurance information, such as the accumulated insurance amount from other insurance companies and the same company. If the sum insured or premium reaches a certain standard, it will also have to engage financial underwriting to review the suitability of the insurance motivation and finances.
In the third phase of claims settlement, Cai Huoyan said that according to the insurance industry insurance fraud risk management work guidelines formulated by the Property and Casualty Insurance Association, the insurance industry should formulate relevant operational standards for insurance fraud risk management. If claims adjusters find specific evidence of insurance fraud, they may report it to the prosecutor’s office to assist in the investigation.
Regarding the insurance status of the woman surnamed Jing, Cai Huoyan said that since the investigation of this criminal case is not open to the public, it is inconvenient to explain it.
Summary FAQ
-
The Financial Supervisory Commission said the current insurance system has multiple anti-fraud checkpoints, including requiring the insured’s consent for third-party insurance, as well as review and reporting mechanisms at each stage of solicitation, underwriting and claims settlement, which can reduce the risk of insurance fraud.
-
According to Article 105 of the Insurance Law, if a third party purchases a death insurance contract, the written consent of the insured must be obtained and the insurance amount must be agreed upon before the contract is valid. Its purpose is to prevent wrongful insurance without consent.
-
When making a request, the purpose and objective of the insurance should be recorded for underwriting reference; When underwriting, check the notification system and check the cumulative sum insured and financial equivalence; If specific evidence of fraud is found during claims settlement, the prosecutor may be notified to assist in the investigation.