
AI summary
Summary of article:
A Japanese couple in their 80s who were receiving a fixed annuity ran into a pension crisis when their 53-year-old unemployed son returned home to live with them. Experts warned that they should create clear financial limits and seek help from public resources.
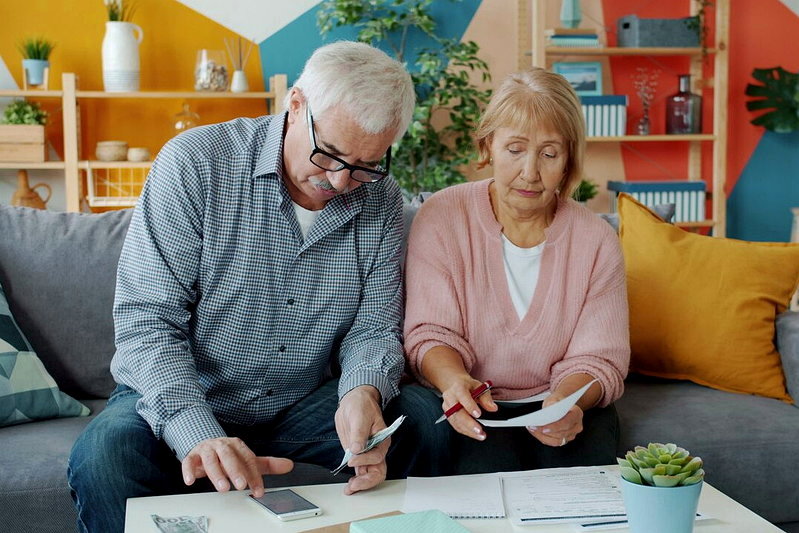
In Asia, it is not uncommon for independent adult children to return to their hometown to live with their elderly parents. However, without clear financial boundaries, an originally stable retirement life is likely to collapse overnight.Japan The media “The Gold 60” reported that an octogenarian couple receiving a monthly pension of 230,000 yen (about US$1,450) faced a financial crisis in their later years after their unemployed 53-year-old son returned home without warning.
The report notes that 82-year-old Masaki (pseudonym) and 81-year-old Keiko have 12 million yen (about US$76,000) in savings, and their monthly expenses are fully covered by an annuity of 230,000 yen (about US$1,450). Their only wish is to “enjoy their retirement in their own homes”. Unexpectedly, one day, the 53-year-old only son Adun (pseudonym), who was suffering from divorce and unemployment, suddenly returned home to live with her, and all the living expenses were borne by the two elders.
In less than half a year, the couple’s annuity was no longer sufficient, and they were forced to use their savings to meet their expenses. Under tremendous financial pressure and psychological worry, the old father eventually fell ill and was admitted to hospital. Facing growing fears that the elderly mother’s capital is about to run out, but unable to ruthlessly kick their son out of the house, the couple is caught in a dilemma.
In this regard, financial planning consultant Yamaguchi Yukako pointed out that it is not uncommon for children who should have lived independently to return to their parents’ home for various reasons. However, if the live-in relationship lacks clear boundaries, it can put the lives of the parents at risk.
The first step is to secure funds for your parents’ retirement and care. Yamaguchi took Masaki and his wife as an example. If they continue to use their savings to cover the gap in living expenses, their savings will be reduced by 500,000 yen (about US$3,100) each year. If future medical and care expenses are added in, the savings can dwindle even faster.
According to data from the Japan Life Insurance Cultural Center, based on an average care period of 4 years and 7 months, the required care fund per person is approximately 5 million yen (about US$31,000). Therefore, parents should adhere to the principle that their annuities and savings are prepared for future medical treatment, care, end-of-life expenses, and property repairs, and they should truthfully disclose the current state of their assets to their children and make it clear that they cannot provide unlimited funds.
In addition, when faced with the need for long-term care, Shan 﨑 recommends consulting local governments as soon as possible and applying for care services or related subsidies. As for employment-related difficulties faced by children, they can also seek help from public agencies and return to the workplace through job matching and other services to avoid getting trapped in the vicious cycle of pulling each other down.
The key to solving the financial crisis in old age is not to simply endure it or give up, but to create clear boundaries and make good use of public resources so that the two generations have a chance to stand on their own feet in life.
Summary FAQ
-
Since the 53-year-old only child had lost his job and returned home after the divorce, all living expenses were borne by his parents. In less than six months, the monthly annuity of 230,000 yen was insufficient, and savings began to be used.
-
Experts say the first thing to protect is funding for medical, nursing, end-of-life and home repairs for the elderly. We cannot provide our children with unlimited support for short-term difficulties, otherwise the security of life in their later years will be seriously eroded.
-
It is recommended that parents openly disclose their assets and affordability, set clear boundaries, and apply for care and subsidized services from the local government. Children should also use public sector support such as employment matching to return to the workplace.